I Dropped Back Below ¥60M ($382K) in Six Weeks — and Found the Hole in My Barista FIRE Plan
My portfolio fell from ¥60.3M to ¥58.5M while the Nikkei rose. What actually moved it, and the one thing my early-retirement plan never accounted for.
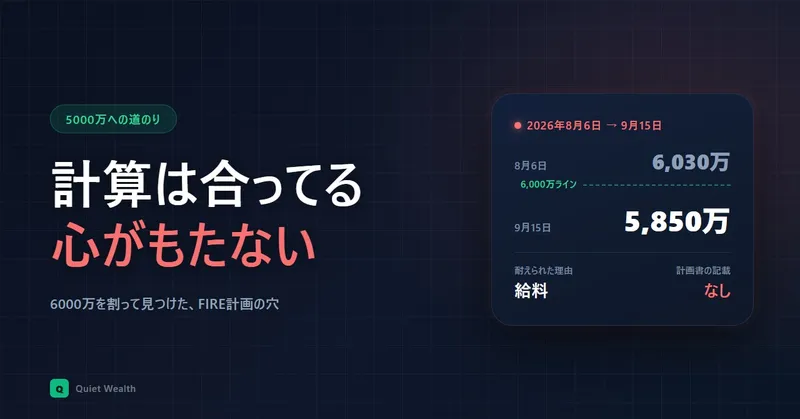
Table of Contents
- Nine days after I wrote that I’d crossed ¥60M, I was back below where I started
- The Nikkei went up. I still went down.
- ”Don’t look at your account” doesn’t survive contact with a normal life
- It turns out my paycheck was doing the work
- My Barista FIRE plan never accounted for this
- The real floor isn’t ¥60M. It’s ¥50M.
- Three things going into the plan
- Falling is part of the plan too
Nine days after I wrote that I’d crossed ¥60M, I was back below where I started
Around September 15, my brokerage account read ¥58.5M — roughly $373,000.
I recognized that number. On August 3 it was ¥57.8M. So the whole climb to ¥60M had unwound almost exactly back to where it started.
I published the post about hitting ¥60.3M on September 6. Nine days later, this.
That post ended with a line I now regret slightly: “reaching ¥60M and living at ¥60M are completely different problems.” Being right about that has still earned me exactly zero yen, but I didn’t expect to be proven right quite so fast.
As of today, September 22, I’m at ¥59.16M — about $382,000. Off the bottom, still under the line.
The Nikkei went up. I still went down.
This is the part that needs explaining.
On September 18 the Bank of Japan raised its policy rate from 1.0% to 1.25% — the highest level since 1995, thirty-one years. Normally a rate hike is a headwind for stocks. Instead the Nikkei jumped more than 1,300 points intraday and closed 882 points higher, in the 65,000 range.
The yen weakened too. Japan hiked, and the yen got sold anyway, from the low 156s to the 157s.
Stocks up, yen weaker. For someone holding dollar-denominated funds from Japan, that combination should be a tailwind twice over.
My account went down anyway.
The explanation is simple: I don’t own the Nikkei. I hold FANG+, NASDAQ 100, and an all-country index fund. Japanese equities barely touch my balance.
Here’s what my side of the ocean actually did:
- S&P 500: 7,718.60 on Sept 4 → 7,619.98 on Sept 14 (about -1.3%)
- NASDAQ: 26,506.99 on Sept 4 → 26,186.41 on Sept 14 (about -1.2%)
The NASDAQ hasn’t set a new high since early June. The reasons being given are nerves around AI — several large U.S. companies have started publicly warning that the technology is moving past what they can control — plus expectations of a Fed rate hike pushing yields up.
Worth noting: my ¥370,000 monthly contribution kept buying through all of this. New money went in and the balance still fell, so the underlying market damage is larger than the headline number suggests.
Watching “Nikkei near record highs” scroll across the morning news while my own account shrinks is a specific kind of disorientation. Eight years in, it still gets me.
On the contributions: I sold nothing, changed nothing, and left my cash allocation alone. Not willpower — the buy order is automated, so stopping it would mean actively canceling something. Do nothing and it buys. There’s no decision available to get wrong.
If I had to name one reason this lasted eight years, that’s it. I’ve written about it before, so I’ll leave it there. What I want to get at this time is what was happening in my head, not in my account.
”Don’t look at your account” doesn’t survive contact with a normal life
The standard advice for a drawdown is to stop looking. Don’t log in. Delete the app. Check once a year.
I can’t do it.
Partly that’s temperament — not looking makes me itchy, even when I’m certain it’s down. I’ve made peace with that.
But there’s a bigger reason.
The morning news runs the Dow.
Turn on the TV and the market comes to you. You don’t have to go get it. So skipping the login doesn’t spare me anything — “U.S. markets closed lower” is already in my head by the time I’ve finished breakfast. If anything, not knowing the exact number is worse. Vague dread beats a specific loss about zero percent of the time.
So I didn’t change a thing. I looked every day, all the way down.
“Don’t look” is advice for an environment where you can actually block the information. With a TV and a phone in a normal household, it isn’t a real option.
Which raises the question of what was holding me together. When I dug into that, I got an answer I wasn’t expecting.
It turns out my paycheck was doing the work
Honestly: this one landed harder than I expected.
I’m still in it. I can’t write this up as something I got through, because I haven’t.
When I asked myself why I was managing at all, the answer came back embarrassingly simple. My salary.
The portfolio dropped ¥1.8M, and on the 25th my paycheck arrived anyway. Bills got paid. The ¥370,000 contribution came out of income, not out of the portfolio. Across the entire drawdown, nothing about my actual life changed by a single yen.
The account can fall without my life taking any damage. That structure was absorbing the shock.
So far, so obvious. The problem is what comes next.
My Barista FIRE plan never accounted for this
Back in April I wrote a full plan to go Barista FIRE at 50. Portfolio projections, withdrawal amounts, my daughter’s education costs, the gap years before the pension starts, a simulation out to age 90. I’d run the first version of those numbers at ¥50M nine days earlier. Two posts, and I thought I’d been thorough.
I reread the plan this week and found what’s missing.
There is not one line anywhere in it about whether I can psychologically survive a period when the portfolio is falling.
What the plan says is: earn 4% a year, withdraw ¥280,000 a month. The math works. But that math quietly assumes the portfolio is going up, or at worst sideways.
So what happens in the other case?
- The portfolio is falling
- I’m withdrawing from it, so it falls faster
- And there’s no paycheck
The shock absorber that carried me through this month doesn’t exist after I quit. The same ¥1.8M drop means something entirely different. What currently registers as “well, that’s annoying” becomes “what if this doesn’t stop.”
Thinking that through was genuinely unpleasant.
A plan can be arithmetically sound and still fail, because the person executing it taps out partway. The 4% rule was derived from market history. It makes no promises whatsoever about the nervous system of the guy checking the balance.
The real floor isn’t ¥60M. It’s ¥50M.
One other thing got clear this month.
Falling through ¥60M made me gloomy, but it didn’t make me alarmed. In the last post I said ¥60M was a psychological marker rather than a switch that triggers any action. Turns out that was exactly right. Nothing fired.
¥50M would be different. I think that one would genuinely scare me.
There’s a reason. Getting to ¥50M took me eight years, and it was the first milestone that felt like it meant something. Going back under it would mean erasing years of accumulation, not months.
So ¥60M is a milestone and ¥50M is a floor. Same kind of round number, completely different jobs.
Last time I argued that milestones should be dates, not amounts, and I still think that. But this month added a wrinkle: the number you’re aiming at and the number you’re defending are two different numbers.
Three things going into the plan
Writing this out, I know what the plan is missing.
First, real drawdown data. Not “assume a 5% annual decline” — the actual number I lived through (¥1.8M over six weeks, roughly 3%) and how it actually felt. An assumption with no lived experience behind it doesn’t hold up when it matters. I built myself an app that counts down the days to FIRE and I check it every morning, but it only knows how to project upward. It needs a down case.
Second, a written floor. What do I do if I break ¥50M? Nothing? Take on more contract work? Pause withdrawals? If it isn’t decided in advance, it gets decided by whatever mood I’m in that morning.
Third, a replacement shock absorber. The plan pencils in ¥200,000 a month of contract income after 50. I need to stop treating that as income and start treating it as the thing that stands in for the paycheck. In that framing, the amount matters less than whether it’s uninterrupted.
I haven’t done any of it yet. This month I only got as far as finding the gap.
Falling is part of the plan too
Eight years in, I’ve had plenty of practice at portfolios going up. I’ve had a decent amount of practice at not selling during a crash.
Grinding down over weeks is a different muscle, and I’d never trained it. A crash is over in a day. This just kept going.
Six weeks was enough to measure how much of that muscle I actually have. The answer is: barely enough. And that’s with a paycheck strapped on for support.
If early retirement means running without the support, I’m glad I took the measurement first.
Tomorrow looks the same as today. Open the app on contribution day, confirm the purchase cleared, close it. Whether the number sits above ¥60M or below it, that part hasn’t changed in eight years.
This applies outside Japan and outside FIRE: any plan that only models the good case is a plan you haven’t tested. Find out what the bad case costs you while you can still afford to be wrong.
What it’s like when the portfolio is falling and work isn’t going well at the same time — that part I wrote about on Note.
Dollar figures use ¥155 = $1, roughly the rate during the period described. This post records my own experience and isn’t a recommendation of any specific investment or strategy. Your decisions are your own.
Related Articles
What Pushed Me Past ¥60M ($387K) Wasn't 8 Years of Investing — It Was 3 Days in August
On Aug 3 my portfolio sat at ¥57.8M. On Aug 6 it hit ¥60.3M. What actually did it, and why I'm not moving my Barista FIRE date up.
I Keep Getting Within a Hair of ¥60M ($400K) — and Keep Getting Knocked Back to $387K
My portfolio touches ¥59M, then slides back to ¥58M without crossing ¥60M. Why a bigger portfolio moves $4,000+ a day, and why I changed nothing.
Side FIRE / Barista FIRE at 50 with $330K Assets in Japan: A Full 3.5-Year Plan
Can you Barista FIRE at 50 with $330K? A 46-year-old Japanese salaryman runs the full math: assets, contract income, education costs, drawdown to 90.