How Much Do You Need for Barista FIRE in Your 40s? ¥45M–¥75M — but the Split Matters More
A 47-year-old in Japan with ¥60.5M gives a range, not a number, and explains why ¥10M of it has to sit in cash. The math comes from the 2022 drawdown.
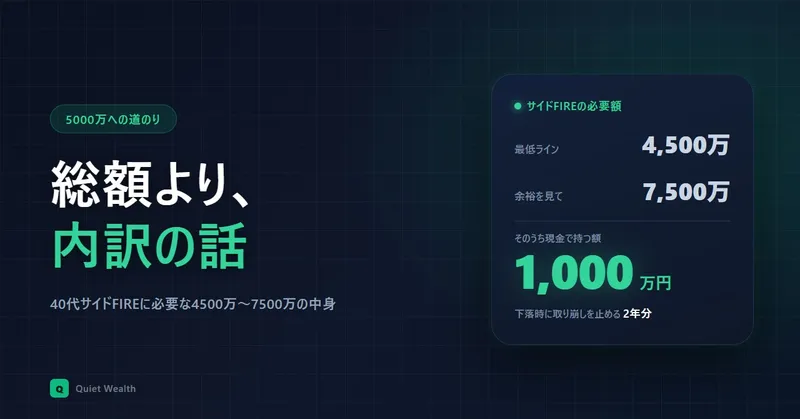
Table of Contents
- Ask me how much you need and I’ll say ¥45M to ¥75M
- Why the range is ¥30M wide
- Quick Japan context
- ”Monthly shortfall ÷ 4%” gives you the wrong answer
- The split matters more than the total
- Why ¥10M? The 2022 drawdown answered it
- There’s exactly one condition that breaks all of this
- You don’t get to FIRE without taking on the part you can’t calculate
Ask me how much you need and I’ll say ¥45M to ¥75M
Most posts on this answer with one number. ¥100M. ¥50M. Pick your favorite.
I can only answer with a range: ¥45M to ¥75M, roughly $290,000 to $484,000.
A ¥30M spread isn’t much of an answer, I know. But the spread is the answer. Two people can both say “Barista FIRE” and mean setups that differ by nearly double.
For context: I’m 47, my portfolio is at ¥60.5M ($390K), and my target is 50. Three years out. I’m sitting right in the middle of my own range.
Why the range is ¥30M wide
Split your costs into what you can cut and what you can’t:
- Housing, food, utilities — hard to cut
- Education — moves in ¥10M increments depending on the path
- Travel and hobbies — infinitely compressible, infinitely expandable
We’re planning public middle school, then private high school and a private humanities university. That’s about ¥10M ($65K) total. Send the kid through public schools the whole way and the number drops by millions of yen.
So ¥75M is “fund the education, take the trips, don’t flinch at hobbies.” ¥45M is “the lights stay on.”
The plan I wrote in April put the floor at ¥45M. I haven’t moved it. But I’ll say this: if I pulled the trigger at exactly ¥45M, I’d be checking my balance every month with a knot in my stomach.
Quick Japan context
Two things that shape these numbers if you’re reading from outside Japan.
Our public pension doesn’t start until 65, and for my household it’ll come to about ¥200,000 ($1,290) a month combined — well below what we spend. There’s no bridging benefit before that, so the gap years are entirely self-funded.
Also, retirement lump sums here are heavily service-length dependent. Leaving at 50 instead of 60 costs me most of mine. I’m budgeting ¥1M ($6.5K), not the ¥10-30M a full-career employee might see.
”Monthly shortfall ÷ 4%” gives you the wrong answer
The standard method: take your monthly shortfall, multiply by 12, divide by 4%.
Let me actually run it on my numbers.
- Income after 50: wife ¥240,000 + my contract work ¥200,000 = ¥440,000/month
- Spending at 50: about ¥485,000 (¥385,000 living + ¥100,000 education)
- Shortfall: ¥45,000/month, or ¥540,000/year
¥540,000 ÷ 4% = ¥13.5M.
So ¥13.5M ($87K) and I can Barista FIRE.
No.
That calculation only sees ages 50 to 60 — the decade where my wife is working and I’m still billing clients. It stops there.
- 60 to 65: no pension yet. Zero income. The entire cost of living becomes a withdrawal.
- 65 onward: pension covers about ¥200,000. The rest comes out of the portfolio for the next 25 years.
The ¥45,000 shortfall is a ten-year phenomenon. At 60 it jumps to roughly ¥385,000 a month and stays there for five years.
Run it all the way through and the answer changes by an order of magnitude.
Any formula that returns ¥13.5M for Barista FIRE is quietly assuming your side income never stops. It stops.
The split matters more than the total
Here’s what I actually wanted to write about.
Say the number is ¥75M. How do you hold ¥75M? I almost never see this discussed. The posts stop at the total.
Mine looks like this:
- Invested: ¥65M
- Cash: ¥10M
That ¥10M is the point of this post.
I’ve written before about holding cash as an emergency fund. Right now it’s ¥5M, twelve months of expenses. After I quit it goes to ¥10M, twenty-four months.
At the time I only thought of it as insurance. Illness, a gap between contracts, that kind of thing.
Last month I found out it does something else.
Why ¥10M? The 2022 drawdown answered it
In my last post I wrote about watching my portfolio go from ¥60.3M to ¥58.5M. Down ¥1.8M, and it got to me more than I expected.
What carried me was the paycheck. The account shrank; my life didn’t.
After I quit there’s no paycheck, and I’m withdrawing — which means shaving down an asset that’s already falling.
So: don’t withdraw while it’s falling. Live off cash instead.
The only question is how many years of cash.
My gut said two. The basis was 2022. When I checked the actual numbers:
- Jan 3, 2022: S&P 500 peaks at 4,796
- Oct 12, 2022: bottoms at 3,577, down about 25%
- Jan 2024: back to 4,796
Peak to peak, roughly 24 months. The number I’d been carrying around as a feeling matched the record almost exactly.
Which makes the math simple. Pausing a ¥280,000 monthly withdrawal for 24 months costs ¥6.72M ($43K).
And I’m already planning ¥10M. It covers it. No separate bucket required.
In my last post I said my FIRE plan had no line item for surviving a drawdown. That wasn’t quite right. There was no line item, but cash I’d set aside for a different reason happened to cover it anyway.
Getting saved by something you didn’t plan isn’t much of a brag. But it’s a useful thing to tell anyone still doing the math: if you size your emergency fund purely as disaster insurance, you’ll come up short. It has to double as the thing that lets you stop selling during a bad stretch. Size it for both.
There’s exactly one condition that breaks all of this
Everything above rests on a single assumption.
My wife’s ¥240,000 and my ¥200,000 in contract work. That ¥440,000 continuing.
The withdrawal is only ¥280,000 because of it. The ¥10M only lasts two years because of it.
What happens if it breaks:
- Wife stops working (health, caring for a parent): shortfall goes from ¥280,000 to ¥520,000
- Two years of cash then requires ¥12.48M, not ¥6.72M
¥10M no longer covers it.
Same if the contract work doesn’t materialize — arguably the likelier failure. I’d be starting to win clients at 50.
Honestly, this is the weakest part of my plan. Market drawdowns I can put a probability on; there’s a century of data. Whether my wife stays able to work, whether I can land contracts — there’s nothing to simulate.
There’s no number to type into the cell. Yes, I track all of this in a spreadsheet. That one field has been blank the entire time.
You don’t get to FIRE without taking on the part you can’t calculate
Writing this straightened something out for me.
The total, I can calculate: ¥45M to ¥75M. The split, I can calculate: ¥65M invested, ¥10M cash. How long I can ride out a drawdown, I can calculate: 24 months, from the 2022 record.
Turns out most of it is calculable. More than I expected.
And then there’s the residue. Whether my wife keeps working. Whether I can sell my own time at 50. Whether my daughter actually goes private. None of it resolves into a number.
I’ve come around to thinking that taking on that residue is the price of admission.
If every variable resolved, it wouldn’t be early retirement — it would just be a scheduled event. The reason it takes nerve is precisely that part of it won’t resolve. When I first ran these numbers at ¥50M and couldn’t bring myself to move, that was the real blocker. What I was short of wasn’t money. It was the willingness to own the blank cell.
¥60.5M today. Fifty in three years.
The number will probably get there. The blank cell is the harder problem, and I’ve stopped expecting it to fill itself in.
The part about how it actually felt to sit with these numbers — that one’s on Note.
Dollar figures use ¥155 = $1. This post records my own experience and projections; it isn’t a recommendation of any investment or life plan. What you need depends heavily on your own household.
Related Articles
I Dropped Back Below ¥60M ($382K) in Six Weeks — and Found the Hole in My Barista FIRE Plan
My portfolio fell from ¥60.3M to ¥58.5M while the Nikkei rose. What actually moved it, and the one thing my early-retirement plan never accounted for.
What Pushed Me Past ¥60M ($387K) Wasn't 8 Years of Investing — It Was 3 Days in August
On Aug 3 my portfolio sat at ¥57.8M. On Aug 6 it hit ¥60.3M. What actually did it, and why I'm not moving my Barista FIRE date up.
I Keep Getting Within a Hair of ¥60M ($400K) — and Keep Getting Knocked Back to $387K
My portfolio touches ¥59M, then slides back to ¥58M without crossing ¥60M. Why a bigger portfolio moves $4,000+ a day, and why I changed nothing.